News, views and commentary from the telecoms sector across emerging markets and developing countries worldwide

Friday, 21 May 2010

India's cellcos to balk at mandatory switch to solar-powered equipment?

Solar power: mandatory for India's cellcos?

The green credentials of DevelopingTelecomsWatch are pretty weak - this blog has never dedicated an entire article specifically to an examination of the environmental impact of telecoms technology.

Moreover, the only time DTW has discussed 'green' technologies at length, when wind and solar-powered mobile base stations were evaulated more than a year ago, the focus was mainly on cost benefits for operators. Just a cursory mention was made how such solutions compare favourably - in terms of environmental impact - to diesel-powered generators in the vast numbers of sites where electricty distribution infrastructure is inadequate across developing countries.

Even in terms of the narrower arguments about cost control, last April's article was by no means constructed entirely of fulsome praise for wind-powered and solar-powered mobile network infrastructure. It was noted that while running costs can, of course, look very attractive, the costs of investing in new solar panels and wind turbines themselves are not trivial. DTW also reported concerns on the part of the GSM Association about the results of trials of sun and wind-powered base stations.

Mobile operators, then, mindful of these questions, could presumably be resistant to any attempt to make reliance on these green technologies mandatory.

This is precisely the situation which could be facing cellcos in India.

Writing for India's Economic Times earlier this month, Subhash Narayan asserts that the country's government "may ask telecom companies to install solar panels to generate backup power for cellphone towers, a move that could hurt the sector already troubled by a squeeze in margins."

A proposal being finalised by the Ministry of New and Renewable Energy (MNRE), writes Narayan, "is aimed at containing the use of polluting diesel gensets to provide back-up power" and "could increase the cost of network expansion significantly"

"The green drive will prevent these engines of development (telecom towers) from becoming grave environmental hazards," said an official with MNRE. "We are discussing the proposal with various stakeholders. A cabinet note is proposed to be finalised thereafter to get the clearance for the scheme," the official said, requesting anonymity

Predicatably, the industry response, as reported by Narayan of the Economic Times, is not terrible enthusiatic. "This could significantly impact the margins of companies already under pressure due to rising spectrum cost and the cut-throat competition in the sector," said 'an executive with a large private telco'.

Narayan asserts that the Indian government is not keen on providing any subsidy for solar power equipment, but says it could offer them soft loans under refinancing schemes of Indian Renewable Energy Development Agency.

This skepticism from India notwithstanding, one can still find evidence of cellcos in developing countries going down the green power route. Chinese vendor, ZTE, for example, seems to have encouraged MTN's Cameroonian opco to take delivery of an unspecified number of solar-powered base stations.
Share/Save/Bookmark

Thursday, 6 May 2010

Afrique Occidentale & Centrale Com: De retour au Sénégal par demande générale

The Zain-Bharti transaction: How will West African mobile markets be affected?

Mais non! DevelopingTelecomsWatch has not become a francophone blog. The frenchified title of today's offering is in honour of the fact that a noted West African telecoms conference is, after two years in Nigeria, to be hosted in Senegal in June.

Geopolitically, West Africa is defined by the UN as consisting of: Benin, Burkina Faso, Côte d'Ivoire, Cape Verde, Gambia, Ghana, Guinea, Guinea-Bissau, Liberia, Mali, Mauritania, Niger, Nigeria, Senegal, Sierra Leone and Togo. Of these, just four are countries where English is an official language. Of the others, two are Lusophone states and ten are French-speaking.

The organisers of the aforementioned conference have found that this linguistic diversity in the region creates certain challenges for them. Nigeria, as by far the largest market in West Africa, seemed to be the logical place in which to host the event for the last couple of years. Certainly, relocating the conference to Abuja (from its previous venue of Dakar, Senegal) two years ago paid tremendous dividends in terms of boosted attendance numbers and a good buzz of activity at the 2008 and 2009 iterations of the gathering. This was achieved, however, at the cost of making the event a tad less attractive for delegates from the numerous French-speaking markets. This effect was somewhat mitigated by ensuring that simultaneous English-French translation was available during all conference sessions, but perhaps not as much as was hoped given that this year Informa Telecoms & Media have moved the show back to Dakar again.

Given that delegates from telecoms operators attend for free, Informa monetises its Com World Series events (of which West & Central Africa Com is one) largely by selling sponsorship packages and exhibition space to the telecoms technology vendors that do business with those operators. These vendors will doubtless remain keen on the potential of the large (and fragmented) Nigerian telecoms market and might be concerned about not having a good tradeshow route-to-market to address this now the conference has headed back to Dakar.

With this in mind, I guess, Informa are also running a specifically Nigerian event in Lagos this year. This will make its debut in September.

In the meantime, what can we expect to be discussed at the Dakar gathering?

I guess one hot topic - addressed via offline chitchat if not via presentations and panel discussions - will be the effect of Zain's withdrawal from the region. The Kuwaiti group currently controls opcos in Burkina Faso, Ghana, Niger, Nigeria and Sierra Leone - as well as others in markets elsewhere in sub-Saharan Africa. As discussed ad nauseum in DTW posts passim., all of these are now set to be in the hands of giant Indian cellco Bharti Airtel. DTW's most recent article, mainly a brief exploration of whether India's mobile market is set to consolidate, did a little to talk up the ways in which Bharti Airtel might be able to reinvent Zain Africa by introducing the low-cost business model which it has empoyed on home turf. So let's see how much tougher sub-Saharan markets are set to become for Zain/Bharti's competitors.

This acquistion, however, may yet take a little while longer to conclude. One reason for this could be resistance from the governments of the countries in which the Zain-owned opcos are set to change hands. That said, there have been recent signs of these obstacles being overcome.

Back in March, for example, as reported by India's Economic Times, the Government of Gabon said it "disapproves" of the sale of Zain's Gabonese assets to Bharti Airtel and reserves the right to take "all necessary measures". Late last week, Reuters was reporting that this objection had been resolved.

It will be interesting, then, to see how long it takes to deal with any further problems of this kind. If the difficulties do continue into June, it should be interesting to connect with Tiemoko Coulibaly, Vice President of Zain's Western Africa operations at West & Central Africa Com in Dakar.

There will be many other reasons to attend the event - but connecting with the likes of Mr Coulibaly could be motivation enough for anyone who does business with Zain in Africa and now needs to keep on top of how the change of ownership is set to change the game.
Share/Save/Bookmark

Thursday, 22 April 2010

India: operator space to consolidate while handset market gets more fragmented?

Maarten Pieters: Vodafone India CEO predicts market consolidation

Last week, a broad range of news outlets were carrying the claim that just 31% of the population of India were known to have access to a toilet and 'improved sanitation' in 2008. This is clearly a regrettable state of affairs, with dire consequences for public health, life expectancy and economic development.

Ordinarily, however, it does not follow that the seriousness of an issue always correlates strongly with the willingness of the global media to give it coverage. It was a welcome surprise, then, to see this particular issue given some space even by the website of the thin, brightly coloured newspaper given free at UK railway stations to daily commuters such as myself. After all, this is an organ whose print version dedicates just a few pages to what I would really call 'news' - far more space is given over to celebrity tittletattle and TV listings.

How, then, did this story successfully compete for space even in that kind of context?

The key seems to have been handing the global media an compelling, ready-written headline. The person responsible for doing so in this case appears to be Zafar Adeel, Director of the United Nations University’s Canada-based think-tank, the Institute for Water, Environment and Health.

So how did Dr. Adeel manage to craft a headline sufficiently eye-catching so as to propel this important but unglamorous issue up the news agenda last week? He did so by building it around the assertion that more Indians have access to a mobile phone than to a working toilet. Presumably, the desired effect on readers in Europe and North America was to stimulate a thought process along the following lines: 'More cellphones than toilets? That's crazy! Toilets have been around forever and are one of the most basic facilities expected for a civilised life -  but the mobile phone is a recently invented luxury item.'

Such a characterisation of the mobile device would be understandable when articulated by someone who ticks the following boxes:
  • lives in a wealthy, developed country and has not had the opportunity to see mobile phones being used on the city streets or in the villages of (for example) Kenya, India or Bangladesh
  • is old enough to remember when mobile phones were seen as an expensive status symbol used only by wealthy executives
  • has not thought about how access to communications services can improve the lives of poor people by connecting them with time-saving information and services
Regular readers of this blog, and anyone working in or around the telecoms sector in emerging markets/developing countries, however, would be much less likely to think of mobile phones in this way. They would probably be inclined to realise that is precisely because developing countries have weak infrastructure that the mobile phone has rapidly become a truly vital part of the lives of even very poor people in such nations. Numerous examples of this have been decribed in DTW posts passim. Rather than trawl through all of those, readers might like to look at a nicely succinct round up of observations on this topic, made recently Anand Giridharadas, writing for the New York Times.

Giridharadas observes that there is "a global flowering of innovation on the simple cellphone" and that "from Brazil to India to South Korea and even Afghanistan, people are seeking work via text message; borrowing, lending, and receiving salaries on cellphones; employing their phones as flashlights, televisions and radios." He goes on to assert that "many do all this for peanuts", noting that "in India, Reliance Communications sells handsets for less than [USD] 25, with one-cent-a-minute phone calls across India and one-cent text messages and no monthly charge — while earning fat profits."

Readers of this blog, particularly any working in India's mobile sector, might on one hand take pride in seeing such achievements talked up but may, on the other hand, not fully recognise the idea of an industry revelling in 'fat' profits.

Certainly, the feeling in India may be that at the very low tariff levels referred to by Giridharadas, not all operators may continue to be viable. Sypmathetic to this view is Maarten Pieters, CEO Of Vodafone India. Speaking to the Economic Times last week, Pieters observed: "It’s all about scale because we have very low tariffs here. If you compared the tariffs here, it’s about 10% or what we get in Europe in the Vodafone Group as an average tariff. So, how can you survive as an operator on those low tariffs that is by creating scale and it is very clear that it will not be able for 10 people or 10 operators to create that scale, which means there needs to be some form of consolidation".

Pieters does not expect this consolidation of the mobile market to happen overnight, however, because it would not be facilitated by India's current M&A rules. "So, we first need to see some changes of the rules and then you will probably see consolidation."

Indian mobile operators, then, have to strive for profitability in an extremely tough environment. Quite often, I have heard industry watchers articulate the view that this should equip the country's cellcos very well for meeting the challenges of extracting a profit from developing countries elsewhere in the world. Also out there is the feeling that any Indian MNOs with international ambitions will need to be mindful of quite different challenges they may face.

Writing last month for telecoms.com about the purchase of Zain's African opcos by Bharti Airtel, for example, Matthew Reed observes that "Bharti will be looking to reinvent Zain Africa by introducing the low-cost business model that it has pioneered successfully in India" and "will also be hoping to achieve economies of scale across its Asian and African operations, which together will make it the fifth-largest mobile operator in the world".

Reed does offer words of caution, however, arguing that "operating in Africa does present particular challenges, some of which will be new to Bharti, despite its credentials as an emerging-market operator."

"The takeover of Zain Africa", writes Reed, "will give Bharti operations in 15 different countries, each of which has its own political and regulatory conditions, and some of which present some political risk. The diversity alone will be something new for Bharti, which only had mobile operations in India until it made recent moves into Sri Lanka and Bangladesh."

Reed also observes that while tariffs in Africa have traditonally been rather higher than those Bharti Airtel has to live with on home soil, the giant Indian cellco is entering many African markets at a time when higher levels of competition have more recently been pushing down prices. "In much of sub-Saharan Africa", Reed adds, "the infrastructure is poor and distribution is difficult."

Maarten Pieters of Vodafone India, meanwhile, is almost uniquely well qualified to make predictions about how his company's major competitor is likely to fare as it embarks on its African adventure - between 2003 and 2005, he was the CEO of Celtel International, the collection of African operators acquired by Zain and subsequently sold on to Bharti Airtel. Pieters has also served on the board of Millicom International Cellular, the multinational mobile group whose African assets currently include opcos in Chad, DRC, Ghana, Mauritius, Rwanda, Senegal and Tanzania.

Pieters offers words of encouragement: "Bharti is a very fantastic company. I really admire them. They have done a very good job in India. They have a very good management. If anyone can make a success out of the old Celtel assets, then it’s them. So, I am very happy that they are in good hands."

While, as Pieters argues, consolidation of the Indian mobile operator space may be inevitable, the handset market, conversely, seems to be becoming more fragmented. Priyanka Joshi of the Business Standard writes that "the segment has seen entry of one mobile vendor every month." For the year 2009, Joshi asserts, "new vendors registered a combined market share of 12.3% of the total 101.54 million mobile handset sales."

Examples of new market entrants offered by Joshi include Wynn Telecom. "Starting May this year, writes Joshi, "the company will launch seven dual SIM handsets priced under Rs 5000 and will also get ready to manufacture handsets in India."

Some new entrants, explains Joshi, will build a business around devices tailored to meet the needs of users in India's vast rural areas. Olive Telecommunications  is one example of a company with this strategy.

It will be interesting to observe, then, whether the mobile services and mobile handsets markets do indeed move in these opposite directions - with the former consolidating down to a smaller number of operators of scale and the latter continuing to offer opportunities for innovative new entrants.

Share/Save/Bookmark

Tuesday, 13 April 2010

More chances to network with telecoms and government bigwigs from Turkey, the Caucasus and Central Asia


'tis the season to go networking with telecoms bigwigs from Turkey and the CIS, it seems. Having not long returned from one industry talking shop in Istanbul, DTW is hoping very much to be able to attend another one later this month.

The conference in question is the 9th annual Caspian Telecoms event, to be held in the city's Hilton Hotel on 28th and 29th April. DevelopingTelecomsWatch is proud to have joined the conference's roster of media partners for the first time this year.

In the coming days, I will take the time to say more about this event and why it may well be worth attending for anyone doing business with telcos, telecoms regulatory agencies and telecoms/IT/information ministries of the countries in this region.

For now, I would simply encourage readers to follow the links in this short introductory note and review the organiser's web site.
Share/Save/Bookmark

Wednesday, 7 April 2010

Eurasia Com: doing the business in Turkey and the CIS

Back in January, I wrote about the Eurasia Com conference which the good folks at Informa Telecoms & Media host annually in Istanbul, taking place in either March or April. At the time, I thought it was unlikely that I would be able to attend. Happily, it did turn out to be possible after all,  meaning that I am able to report some of what was discussed at the Conrad Hotel on 23rd and 24th March.

For those not familiar with the event or with the wider series of related conference-plus-exhibition events of which it is a part, a few words of explanation:
  • Informa's Com World Series evolved from what was once known as the GSM (and later GSM>3G) World Series of events. The GSM series was itself a spin-off of the GSM World Congress (now Mobile World Congress), of which Informa was the original founder.
  • The GSM World Series brought scaled-down versions of the main event to a selection of locations ranged around the world's emerging markets. In each location, the aim was to gather large numbers of decision-makers from the mobile operators of the region around the host city. These locations included cities in Africa, Asia, Latin America and Central and Eastern Europe.
  • The Com World Series brand was introduced a few years ago to reflect a perceived need to offer meeting points for a broader community than just GSM mobile operators. The organisers were mindful of the idea that the previously quite sharp fixed-mobile distinction was becoming increasingly fuzzy around the world. They thought about what had once been pure play mobile operators offering other kinds of broadband service, either by building new networks (copper, fibre, fixed-wireless) or in partnership with established fixed-line operators. They thought about new mobility propositions from companies whose previous offerings had not been in the cellular space. They thought about incumbent fixed-line operators merging with previously quite separate mobile business units (think in terms of what Deutsche Telekom is doing all over the CEE region).
  • Throughout this evolution, Informa's series of events has stuck to a pretty successful business model, which is still in place today - operators (and other telecoms service providers) attend for free, with most of the revenue coming from any organisations with products and services to sell into the operator space. This includes the major network technology vendors and all manner of software companies, systems integrators, consultancies etc.
  • Eurasia Com is a relatively new part of the Com World Series, although this year's iteration was the fourth to take place in Istanbul, having been relocated from Almaty, Kazakhstan, where the event first took place in 2006.
  • The challenge which the organisers face - and which I feel they met pretty successfully this year - is bringing together a crowd from what are quite diverse markets. A large Turkish contingent (representing the likes of Turk Telekom, Vodafone Turkey, Turkcell, Avea and Koc.net) mixes with delegates from the former Soviet republics of Central Asia and the Caucasus, making it necessary to arrange for everyone to gain from presentations in Turkish, Russian and English. If you attend next year, expect to spend some time wearing a headset which pipes the simultaneous interpretation right into your ears.
That, then, is a little about the event, its origins and how it works on the day. The challenge mentioned above (making the conference relevant for both Turkish delegates and for guests from the CIS) was dealt with this year by having elements of the second day billed specifically as a 'Turkey focus' session, thereby acknowledging that there probably do exist some differences between the concerns of the local audience of those of the visitors from the former Soviet republics where market conditions are quite different.

I am pleased to report that this worked well. As a veteran of more conferences than I care to remember, I have got used to seeing events looking busy on day one and feeling a lot less vibrant on the second day. At Eurasia Com 2010, delegate numbers were, I think, possibly even higher on 24th March than they had been on 23rd.

So, what was discussed during these two days of slideware, panel sessions and offline networking? Well, in the sessions I managed to catch, highlights included:
  • Informa analyst Gemma Bunting cautioning delegates to remain open minded about real mobile penetration rates across the CIS, noting that multi-SIM usage makes accurate measurement quite difficult and pointing out that in the supposedly saturated Russian market over 20 million subscriptions were added by operators last year.
  • Informa's Bunting noting that ARPU is declining sharply in some markets - Uzbekistan was given as an example - USD 9/month in 2007, dropping to USD 4/month by 2009.
  • Gemma Bunting wondering about the impact of Tele2's acquisition of a mobile operation in Kazakhstan and observing that the Swedish group is known for its aggressive pricing.
  • Ineke Botter, CEO of Azeri cellco Bakcell indicating the a mobile money offering from her company might not be iminent but was certainly "on the roadmap".
  • Mustafa Kiral of Russian telecoms investment group Altimo indicating that his company is in the market for opportunities to acquire majority stakes in telecoms operators in emerging markets - African markets were mentioned.
  • Altimo's Kiral sounding lukewarm at best when the conference Chairman asked if Altimo is considering investments in the wireline space.
  • Mehmet Hasanov of Aztelekom talking up the revenue potential of the wholesale business and wondering why telcos' marketing people are generally so inclined not to get excited about it.
  • A few snippets about the planned privatisation of Tajiktelecom.
I was not surprised, also, to learn more in offline conversations than I did from listening to presentations. The lesson here, for those few conference veterans who do not already know, is that it's important to get proactive at these gatherings - get among the delegates and speakers, working the room and maximising the opportunity to develop a good number of valuable contacts under one roof.

My guess is that 2009 was at least moderately challenging for conference organisers and that delegate numbers across the events industry may have been negatively affected by financial worries on the part of target audiences. My recent experience in Istanbul, however, just went to confirm that there continues to be no substitute for making face-to-face contact with potential new clients and partners and that events of this type can be a pretty good one-stop-shop for doing so. I would also particularly recommend this and other events in Informa's Com World Series for the way in which they gather crowds from given higher growth regions around the globe.
Share/Save/Bookmark

Wednesday, 31 March 2010

Zain Africa Done Deal Watch

Former Zain CEO Al Barrak - exit from Africa caused his departure?
During 2009 DevelopingTelecomsWatch became somewhat preoccupied with the fate of the African assets of MEA mobile powerhouse Zain. As speculation mounted about whether these operations were up for sale and, if so, who the prospective purchasers might be, DTW managed to churn out no less than thirteen Zain-themed articles, the first of these appearing on 12th June. Scratching away at persistent rumours like a mutt with fleas, this blog was still whining on about the story on 18th August.

The whole series of ramblings rejoiced in the clunky title 'Zain Africa Speculation Watch', which has been revived and paraphrased here with today's offering.

Along the way, a number of potential suitors for Zain's African opcos got a mention. These included France Telecom and Vivendi plus Indian operators Reliance Communications and BSNL.

All these months later, it seems fairly safe to assert that the speculation stage is finally over, with shares in another Indian cellco, Bharti Airtel, edging higher on the back of news that it will sign a USD 10.7 billion deal to acquire the Zain's African telecom assets later today.

If, as now appears to be virtually certain, the Indian MNO does manage to conclude this deal, it will be a case of third time lucky, as noted recently by Shalini Singh of the Times of India, who reminds us of Bharti Airtel's two fruitless attempts to engineer a tie-up with South Africa's MTN, another saga which had some coverage here at DTW. As well as observing that the Zain Africa purchase will "catapult Bharti to the rank of the sixth-largest telecom service provider in the world by number of subscribers", Singh feels that it is "an ironic twist of fate" that one of the Indian firm's major competitors in its new markets will be MTN.

With this mega-deal now on the brink of proceeding, perhaps the time is right to ask that Bharti Airtel has to gain (and lose) from competing in so many new markets at once, and to ask what motivated Zain to quit Africa less than five years after entering the continent's mobile arena via the acquisition of Mohamed Ibrahim's Celtel International.

James Middleton of telecoms.com writes that "for Zain, the deal represents a retrenchment of the company's strategy as well as good value." Middleton argues that while the company has succeeded in transforming its brand and in building up an impressive customer base across sub-Saharan Africa, it has struggled to operate profitably.

Quoted in James's article is his fellow Informa Telecoms & Media employee Nick Jotischky, a principal analyst with the firm. "Perhaps it turned to the managed services model too late in the day and failed to leverage its supplier relationships so as to build in sufficient economies of scale", says Jotischky, who suggests that this is where Bharti Airtel will focus its efforts.

"Whilst it will, no doubt, be confident of controlling its costs, Airtel will aim to build up its brand equity characterised by reliability very quickly," says Jotischky. "But reliability alone will not be enough – the newcomer will have to show itself to be innovative as well. In an already competitive marketplace, Bharti will not just be competing with other mobile operators for a share of wallet but with other brands in adjacent consumer goods sectors. This means that Bharti will be under pressure to offer services that are directly relevant to end-users and this will differ from market to market."

James Middleton talks up the chances of the Indian cellco maximising the value of this large new investment. "Bharti has a heritage in making network sharing and outsourcing deals work and will not be afraid of being aggressive on per minute pricing," he writes. "The company is also well versed in addressing the difficulties of serving a largely rural, high-churn, low-revenue market."

Inspired by this transaction, Informa's telecoms.com is currently running a series of articles offering 'ten tips for investing in Africa'.

Informa offer their first tip, that operators need to be innovative on pricing, while noting that mobile tariffs in much of Africa are high compared to those in some other emerging markets. "For example", runs the telecoms.com article, "Zain Kenya’s lowest tariff is about [USD] 0.04 per minute, for on-net calls.. compared to India, where Reliance Communications offers tariffs that are as low as [USD] 0.01 per minute, for both on-net and off-net calls." The article continues by pointing out that the fact that tariffs in Africa are relatively high is reflected in ARPU levels: "In 4Q09 blended monthly ARPU across Africa as a whole was [USD] 10.49 – but in India blended monthly ARPU in 4Q09 was much lower, at just [USD] 2.73, and falling.

However, the article observes that mobile tariffs have already come down in many African markets in the past couple of years as competition has intensified, often because of the market entry of new operators. Usage in Africa, meanwhile,  the article contends, has increased over the past couple of years too. African MoU, however, remains "half that of India's, which does suggest that there is potential for substantial further growth."

This growth opportunity notwithstanding, the gist of Infoma's 'tip' is that "African operators are probably best advised to avoid getting into the kind of price wars that are taking place in the Indian market", where ARPU halved during 2009, creating a big squeeze on  operators' profits.

Rather, Informa advises, "African operators should aim to demonstrate more of the innovation in pricing that is already evident on the continent through plans such as Zain's One Network, which allows subscribers to pay local rates when roaming, and MTN's MTN Zone, a dynamic tariff plan that charges lower rates when the network is not busy."

Let's see whether Bharti Airtel considers this to be sage advice as it embarks on its African adventure.

On a personal note, I will be interested to see whether the Indian cellco will make many changes to the management teams running its numerous newly-acquired opcos - and to listen out for a sense of how far Zain's people around Africa welcome the change of ownership. One opco CEO apparently quite upbeat about all of this is Zain Zambia MD David Holiday:


Presumably less positive about Zain's sales of its African assets is the man who masterminded their acquisition for the Kuwaiti group, former CEO Saad al Barrak, who resigned in February.

At the time, Emeka Obiodu, a senior analyst at Ovum, said: "Al Barrak championed this expansion push – buying Celtel, and aiming to make Zain one of the top ten mobile operators by 2011. But his whole ambition was blown to pieces by the owners who wanted to sell off in Africa."

While Al Barrak and his strategy do appear to have some detractors, Obiodu does not seem to be among them: "He’s taken MTC, this small company from Kuwait and transformed it into Zain, a global mobile powerhouse. He didn't bite of more than he can chew, but his vision diverged from the vision of the owners. When we did some financial analysis on Zain, the company wasn’t doing particularly badly. It wasn’t like he ran the business into the ground, although you have to concede that some of the small markets in Africa were seriously under-performing."

Now we will see whether Bharti Airtel has the patience and vision to stay in these numerous African markets for longer than Al Barrak's former company elected to do.
Share/Save/Bookmark

Friday, 19 March 2010

East African opportunities unclear as cellcos remain coy about data ARPU

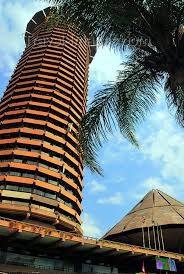
Kenyatta Int'l Conference Centre, Nairobi: venue for this year's East Africa Com

Last year I had the pleasure of visiting Nairobi, Kenya for the first time, building meetings around the excellent East Africa Com conference and exhibition.

This year, given that my day-to-day commercial activity now does not give me much exposure to Africa, I will not attending. Were I still more active in Africa, however, I would certainly want to be there - and I would encourage anyone who does business with the telecoms operators of the East Africa region to head for the Kenyatta International Conference Centre on 27th-28th April.

This year's event will be graced by the presence of the Hon. Samuel Poghisio, the host country's Minister for Information & Communications and by Charles J.K Njoroge, Director General of telecoms regulatory agency the CCK (Communications Commission of Kenya). I don't recall the Kenyan Government and authorities being represented at such a high level at the 2009 event, so the organisers are to be congratulated for the upgrade.

Sponsors and exhibitors will doubtless also be impressed by the number of operator CEOs to whom they will have access during the two days of discussions. Of these, two of the biggest hitters are Michael Ghossein, CEO of France Telecom-controlled Telkom Kenya, the country's incumbent fixed-line operator and Michael Joseph, the long-standing CEO of Kenya's dominant (78.8% market share, according to WCIS) mobile operator Safaricom.

This may be one of the final conferences appearances for the latter, Joseph having announced his impending retirement. He joined the Kenyan operator in mid-2000, when Vodafone first invested in the company. Since then, he has guided the company from a subscriber base of fewer than 20,000 to over 15 million today. Along the way, Safaricom has become renowned for its M-Pesa mobile money transfer service, which has brought the advantages of financial services to very large numbers of Kenya's largely 'unbanked' population. Safaricom also attracted praise this week from Alexander Grouet of Mira Networks, a leading provider of connectivity and billing tools between business and mobile networks in Africa.

Grouet asks: "Would you plan a trip to a foreign destination if you didn't know what the place looked like, what there was to see, how much a hotel room cost and what local transportation was available?" Having concluded that most readers would not, Grouet then invites us to imagine that what we’re talking about is not your vacation, but your business. "Well that’s pretty much what it’s like for most content providers wanting to penetrate the SSA [sub-Saharan Africa] market", he continues. "Despite the hype, the market metrics WASPs crucially need in order to make the next step, such as data ARPU or WAP traffic, are virtually inaccessible. Even traditional market data resellers don't offer it, as optimistically named Africa VAS reports almost exclusively include blended indicators rather than content-specific ones." I don't recall if this is a fair accusation to direct towards the good folks at the reports business of Informa Telecoms & Media, the organisers of East Africa Com.

Even if it is, Grouet suggests that the fault for the scarcity of these vital data lies with operators. "Out of the 26 operators in the 5 countries I worked on last year (Nigeria, Kenya, Ghana, Senegal and Cote d'Ivoire) only 2 to my knowledge," he writes, "publicly released their data ARPU." The two cellcos in Mr. Grouet's good books are Safaricom and Starcomms, a Nigerian CDMA carrier.

"The most likely explanation for this", ventures Grouet, "is that the data figures are still so low on most networks that operators simply don’t want to release them at this stage." According to Grouet, even Safaricom's data ARPU, including M-Pesa, stands at just USD 1 monthly, while the figure for Starcomms, including EV-DO dongles, is just under USD 2 per month. "But at least, we know where they stand, and we will be able to measure their progress when they next update those figures," Grouet continues.

Grouet hopes that other African operators will break their silence on the topic of data revenues, not least because that unwillingness to share data "only has the counter-productive effect of making it harder for international content companies, who precisely could help operators boost their data traffic, penetrate their markets."

Let's see how many cellco attending East Africa Com agree with these sentiments. Were I to attend this year, I would probably like to pursue that line of questioning, not least because I have received marketing emails from Informa which suggests that the region's operators are somewhat focused on data services.

A speaker likely to turn in an entertaining presentation is Noel Herrity, CEO of Tanzania's Zantel, an operator in which the UAE's Etisalat owns a 51% stake. Mr. Herrity delivered a compelling, nicely paced talk at the 2009 iteration of the conference and delegates will be hoping for more of the same. Perhaps we can be optimistic about that - Herrity may be in buoyant mood in light of recent reports indicating that the operator has begun recording net customer additions again, following two quarters of net loss.

One speaker for whom it could be challenging to stay 'on message'? Bashar Arafeh, the COO of the East Africa Region for MEA mobile group Zain.

This might arise as a result of delegates' curiosity about the future of Zain's African operations. Subject to takeover speculation for many months now (see DTW articles passim.), these assets could well be the property of giant Indian cellco Bharti Airtel before too long. The most recent developments in this long-running saga may soon prompt a revival of the popular mini-series (well, it generated more hits than usual) which appeared here on-and-off for much of 2009, rejoicing in the clunky title 'Zain Africa Speculation Watch' (and variations thereon).

Other CxOs appearing on stage at next months event include:
I'm sure this year's event will once again be a useful place to do business, gain market intelligence and enjoy the company of a crowd who always seem very open to networking and making new contacts.
Share/Save/Bookmark