News, views and commentary from the telecoms sector across emerging markets and developing countries worldwide
Showing posts with label Kenya. Show all posts

Wednesday, 31 March 2010

Zain Africa Done Deal Watch

Former Zain CEO Al Barrak - exit from Africa caused his departure?
During 2009 DevelopingTelecomsWatch became somewhat preoccupied with the fate of the African assets of MEA mobile powerhouse Zain. As speculation mounted about whether these operations were up for sale and, if so, who the prospective purchasers might be, DTW managed to churn out no less than thirteen Zain-themed articles, the first of these appearing on 12th June. Scratching away at persistent rumours like a mutt with fleas, this blog was still whining on about the story on 18th August.

The whole series of ramblings rejoiced in the clunky title 'Zain Africa Speculation Watch', which has been revived and paraphrased here with today's offering.

Along the way, a number of potential suitors for Zain's African opcos got a mention. These included France Telecom and Vivendi plus Indian operators Reliance Communications and BSNL.

All these months later, it seems fairly safe to assert that the speculation stage is finally over, with shares in another Indian cellco, Bharti Airtel, edging higher on the back of news that it will sign a USD 10.7 billion deal to acquire the Zain's African telecom assets later today.

If, as now appears to be virtually certain, the Indian MNO does manage to conclude this deal, it will be a case of third time lucky, as noted recently by Shalini Singh of the Times of India, who reminds us of Bharti Airtel's two fruitless attempts to engineer a tie-up with South Africa's MTN, another saga which had some coverage here at DTW. As well as observing that the Zain Africa purchase will "catapult Bharti to the rank of the sixth-largest telecom service provider in the world by number of subscribers", Singh feels that it is "an ironic twist of fate" that one of the Indian firm's major competitors in its new markets will be MTN.

With this mega-deal now on the brink of proceeding, perhaps the time is right to ask that Bharti Airtel has to gain (and lose) from competing in so many new markets at once, and to ask what motivated Zain to quit Africa less than five years after entering the continent's mobile arena via the acquisition of Mohamed Ibrahim's Celtel International.

James Middleton of telecoms.com writes that "for Zain, the deal represents a retrenchment of the company's strategy as well as good value." Middleton argues that while the company has succeeded in transforming its brand and in building up an impressive customer base across sub-Saharan Africa, it has struggled to operate profitably.

Quoted in James's article is his fellow Informa Telecoms & Media employee Nick Jotischky, a principal analyst with the firm. "Perhaps it turned to the managed services model too late in the day and failed to leverage its supplier relationships so as to build in sufficient economies of scale", says Jotischky, who suggests that this is where Bharti Airtel will focus its efforts.

"Whilst it will, no doubt, be confident of controlling its costs, Airtel will aim to build up its brand equity characterised by reliability very quickly," says Jotischky. "But reliability alone will not be enough – the newcomer will have to show itself to be innovative as well. In an already competitive marketplace, Bharti will not just be competing with other mobile operators for a share of wallet but with other brands in adjacent consumer goods sectors. This means that Bharti will be under pressure to offer services that are directly relevant to end-users and this will differ from market to market."

James Middleton talks up the chances of the Indian cellco maximising the value of this large new investment. "Bharti has a heritage in making network sharing and outsourcing deals work and will not be afraid of being aggressive on per minute pricing," he writes. "The company is also well versed in addressing the difficulties of serving a largely rural, high-churn, low-revenue market."

Inspired by this transaction, Informa's telecoms.com is currently running a series of articles offering 'ten tips for investing in Africa'.

Informa offer their first tip, that operators need to be innovative on pricing, while noting that mobile tariffs in much of Africa are high compared to those in some other emerging markets. "For example", runs the telecoms.com article, "Zain Kenya’s lowest tariff is about [USD] 0.04 per minute, for on-net calls.. compared to India, where Reliance Communications offers tariffs that are as low as [USD] 0.01 per minute, for both on-net and off-net calls." The article continues by pointing out that the fact that tariffs in Africa are relatively high is reflected in ARPU levels: "In 4Q09 blended monthly ARPU across Africa as a whole was [USD] 10.49 – but in India blended monthly ARPU in 4Q09 was much lower, at just [USD] 2.73, and falling.

However, the article observes that mobile tariffs have already come down in many African markets in the past couple of years as competition has intensified, often because of the market entry of new operators. Usage in Africa, meanwhile,  the article contends, has increased over the past couple of years too. African MoU, however, remains "half that of India's, which does suggest that there is potential for substantial further growth."

This growth opportunity notwithstanding, the gist of Infoma's 'tip' is that "African operators are probably best advised to avoid getting into the kind of price wars that are taking place in the Indian market", where ARPU halved during 2009, creating a big squeeze on  operators' profits.

Rather, Informa advises, "African operators should aim to demonstrate more of the innovation in pricing that is already evident on the continent through plans such as Zain's One Network, which allows subscribers to pay local rates when roaming, and MTN's MTN Zone, a dynamic tariff plan that charges lower rates when the network is not busy."

Let's see whether Bharti Airtel considers this to be sage advice as it embarks on its African adventure.

On a personal note, I will be interested to see whether the Indian cellco will make many changes to the management teams running its numerous newly-acquired opcos - and to listen out for a sense of how far Zain's people around Africa welcome the change of ownership. One opco CEO apparently quite upbeat about all of this is Zain Zambia MD David Holiday:


Presumably less positive about Zain's sales of its African assets is the man who masterminded their acquisition for the Kuwaiti group, former CEO Saad al Barrak, who resigned in February.

At the time, Emeka Obiodu, a senior analyst at Ovum, said: "Al Barrak championed this expansion push – buying Celtel, and aiming to make Zain one of the top ten mobile operators by 2011. But his whole ambition was blown to pieces by the owners who wanted to sell off in Africa."

While Al Barrak and his strategy do appear to have some detractors, Obiodu does not seem to be among them: "He’s taken MTC, this small company from Kuwait and transformed it into Zain, a global mobile powerhouse. He didn't bite of more than he can chew, but his vision diverged from the vision of the owners. When we did some financial analysis on Zain, the company wasn’t doing particularly badly. It wasn’t like he ran the business into the ground, although you have to concede that some of the small markets in Africa were seriously under-performing."

Now we will see whether Bharti Airtel has the patience and vision to stay in these numerous African markets for longer than Al Barrak's former company elected to do.

Share/Save/Bookmark

Friday, 19 March 2010

East African opportunities unclear as cellcos remain coy about data ARPU

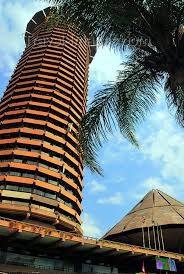
Kenyatta Int'l Conference Centre, Nairobi: venue for this year's East Africa Com

Last year I had the pleasure of visiting Nairobi, Kenya for the first time, building meetings around the excellent East Africa Com conference and exhibition.

This year, given that my day-to-day commercial activity now does not give me much exposure to Africa, I will not attending. Were I still more active in Africa, however, I would certainly want to be there - and I would encourage anyone who does business with the telecoms operators of the East Africa region to head for the Kenyatta International Conference Centre on 27th-28th April.

This year's event will be graced by the presence of the Hon. Samuel Poghisio, the host country's Minister for Information & Communications and by Charles J.K Njoroge, Director General of telecoms regulatory agency the CCK (Communications Commission of Kenya). I don't recall the Kenyan Government and authorities being represented at such a high level at the 2009 event, so the organisers are to be congratulated for the upgrade.

Sponsors and exhibitors will doubtless also be impressed by the number of operator CEOs to whom they will have access during the two days of discussions. Of these, two of the biggest hitters are Michael Ghossein, CEO of France Telecom-controlled Telkom Kenya, the country's incumbent fixed-line operator and Michael Joseph, the long-standing CEO of Kenya's dominant (78.8% market share, according to WCIS) mobile operator Safaricom.

This may be one of the final conferences appearances for the latter, Joseph having announced his impending retirement. He joined the Kenyan operator in mid-2000, when Vodafone first invested in the company. Since then, he has guided the company from a subscriber base of fewer than 20,000 to over 15 million today. Along the way, Safaricom has become renowned for its M-Pesa mobile money transfer service, which has brought the advantages of financial services to very large numbers of Kenya's largely 'unbanked' population. Safaricom also attracted praise this week from Alexander Grouet of Mira Networks, a leading provider of connectivity and billing tools between business and mobile networks in Africa.

Grouet asks: "Would you plan a trip to a foreign destination if you didn't know what the place looked like, what there was to see, how much a hotel room cost and what local transportation was available?" Having concluded that most readers would not, Grouet then invites us to imagine that what we’re talking about is not your vacation, but your business. "Well that’s pretty much what it’s like for most content providers wanting to penetrate the SSA [sub-Saharan Africa] market", he continues. "Despite the hype, the market metrics WASPs crucially need in order to make the next step, such as data ARPU or WAP traffic, are virtually inaccessible. Even traditional market data resellers don't offer it, as optimistically named Africa VAS reports almost exclusively include blended indicators rather than content-specific ones." I don't recall if this is a fair accusation to direct towards the good folks at the reports business of Informa Telecoms & Media, the organisers of East Africa Com.

Even if it is, Grouet suggests that the fault for the scarcity of these vital data lies with operators. "Out of the 26 operators in the 5 countries I worked on last year (Nigeria, Kenya, Ghana, Senegal and Cote d'Ivoire) only 2 to my knowledge," he writes, "publicly released their data ARPU." The two cellcos in Mr. Grouet's good books are Safaricom and Starcomms, a Nigerian CDMA carrier.

"The most likely explanation for this", ventures Grouet, "is that the data figures are still so low on most networks that operators simply don’t want to release them at this stage." According to Grouet, even Safaricom's data ARPU, including M-Pesa, stands at just USD 1 monthly, while the figure for Starcomms, including EV-DO dongles, is just under USD 2 per month. "But at least, we know where they stand, and we will be able to measure their progress when they next update those figures," Grouet continues.

Grouet hopes that other African operators will break their silence on the topic of data revenues, not least because that unwillingness to share data "only has the counter-productive effect of making it harder for international content companies, who precisely could help operators boost their data traffic, penetrate their markets."

Let's see how many cellco attending East Africa Com agree with these sentiments. Were I to attend this year, I would probably like to pursue that line of questioning, not least because I have received marketing emails from Informa which suggests that the region's operators are somewhat focused on data services.

A speaker likely to turn in an entertaining presentation is Noel Herrity, CEO of Tanzania's Zantel, an operator in which the UAE's Etisalat owns a 51% stake. Mr. Herrity delivered a compelling, nicely paced talk at the 2009 iteration of the conference and delegates will be hoping for more of the same. Perhaps we can be optimistic about that - Herrity may be in buoyant mood in light of recent reports indicating that the operator has begun recording net customer additions again, following two quarters of net loss.

One speaker for whom it could be challenging to stay 'on message'? Bashar Arafeh, the COO of the East Africa Region for MEA mobile group Zain.

This might arise as a result of delegates' curiosity about the future of Zain's African operations. Subject to takeover speculation for many months now (see DTW articles passim.), these assets could well be the property of giant Indian cellco Bharti Airtel before too long. The most recent developments in this long-running saga may soon prompt a revival of the popular mini-series (well, it generated more hits than usual) which appeared here on-and-off for much of 2009, rejoicing in the clunky title 'Zain Africa Speculation Watch' (and variations thereon).

Other CxOs appearing on stage at next months event include:
I'm sure this year's event will once again be a useful place to do business, gain market intelligence and enjoy the company of a crowd who always seem very open to networking and making new contacts.
Share/Save/Bookmark

Thursday, 17 September 2009

DevelopingTelecomsWatch - age notwithstanding, pleased to be a part of YPBLOGS.com

I'd like to think that I approach everything I do with a reasonable degree of professionalism. Whether it's accurate to describe myself as a young professional, though, is open to question. While I do still feel pretty youthful, it seems that almost half of the thrusting young go-getters who visit YPBLOGS.com feel that a dusty old geezer like your humble scribe is far too long in the tooth to be known as a young professional.

YPBLOGS.com is a fast-growing blog aggregator, currently over 14,000+ articles strong. The site's creator describes it as the place for young professionals to find up to the minute news and information that matters. This is achieved by aggregating blogs - 200+ sites are checked automatically every 10 minutes for updated articles, to which links are posted.

On one hand, the blogs added to the site are very diverse in terms of the topics they cover - banking, personal finance, investments, career advice and new media news are among the fields I've seen discussed. On the other hand, the bloggers who have added their sites seem to be less diverse in terms of where in the world they are located. My observation is that, at present, voices from North America are by far the most numerous. Europeans like myself are a rarer breed at YPBLOGS - and bloggers from developing countries and emerging markets worldwide seem to be rarer still.

I'd like to see this rectified, not least because, as this blog often makes clear, innovative technologies, services and business models are being incubated all over the world - inventiveness is certainly not the sole preserve of those of us living in the most developed economies and the most affluent societies. In the telecoms space, it is in developing countries such as Kenya that bleeding-edge mobile financial services solutions are being developed and refined. That country is even home to the 18-year old mobile services entrepreneur who has developed an SMS-based solution which enables car owners to keep track of their vehicles, offering a defence against theft.

YPBLOGS is a useful arena in which to absorb the ideas of younger bloggers, thinkers and innovators. I feel, however, that this community would be even richer were it to be joined by innovative writers from developing countries. I would therefore urge the many readers of DevelopingTelecomsWatch who hail from Africa, Asia and Latin America to add their voices to the conversations aggregated at YPBLOGS.com - and don't be put off if you're over thirty.

Visitors to YPBLOGS.com were asked: What is the age limit for considering a person a "young professional"? The most common response (49% of respondents so far) was 'under 30'. Well, I don't fit in there - but this has not deterred me from taking advantage of the site or from enjoying the interesting material it aggregates.

So I call for an invasion of the over-30s and from developing countries. We can make YPBLOGS even better.
Share/Save/Bookmark

Sunday, 23 August 2009

Mobile industry nicely balances profit motive with improving lives: not everyone agrees...

It has been a tendency of this blog to eulogise the ways in which telecoms companies with business units in developing countries are able to reconcile efforts to alleviate poverty and misery with their need to turn a profit and grow shareholder value.

I therefore tend to be very encouraged when I read articles such as that written in April by Rohit Singh of the Overseas Development Agency (ODI), a British think tank focused on international development and humanitarian issues. Singh writes about the numerous studies which support the idea that a rapid increase in mobile penetration contributes significantly to economic growth. He discusses the incremental, tranformational and production benefits brought by mobile phones:
  • Incremental benefits: improving what people already do – offering them faster and cheaper communication, often substituting for costly and risky journeys.
  • Transformational benefits: offering something new such mobile banking, enabling the unbanked to store value.
  • Production benefits: resulting from the creation of new livelihoods, not only through professional telecommunications jobs but also through activities like re-selling airtime or phone cards.
Much praise, then, has been directed by DevelopingTelecomsWatch at the efforts of mobile operators worldwide, notably in Africa. None of what has been written here suggests that there might be a possible downside to the rapid growth of mobile infrastructure and services in the places where the world's least affluent people live their lives.

There are those, however, who voice precisely that concern. Notable, I think, is Steve Song, who spent ten years working on ICT for Development issues at the International Development Research Centre (IDRC), a Canadian state-owned enterprise whose role is to help developing countries use science and technology to find practical, long-term solutions to the social, economic, and environmental problems they face. Song is now based in Cape Town, where he has taken up a fellowship with the Shuttleworth Foundation, an organisation which works to drive social and policy innovation in the fields of education and technology through policy dialogue and practical projects.

I was very interested in Steve Song's reaction to Kenyan cellco Safaricom winning a UN-HABITAT award for its M-Pesa mobile money services. This got a mention in the recent discussion here about whether mobile banking and money transfer services branded and run by cellular operators in developing countries might be vulnerable to a competitive threat from apparently operator-neutral solutions such as the one recently announced by Monitise. My own reaction to a cellco being lauded for how its services improve the lives of poor people is always very positive - it makes me pleased to make my living in and around an industry whose technologies can be a force for good. On hearing about Safaricom's award, Steve Song, however, was prompted to consider, not for the first time, "the effective monopolies/oligopolies" that mobile operators in Africa have become.

While Song acknowledges "the miracle that mobile phones are" and says that "there can't be many people who still doubt the direct value that mobile phones provide to people", he is concerned that the wealth that is being generated by cellcos in Africa is being distributed too unevenly. To support this assertion, he cites the case of South Africa's MTN apparently acknowledging that is subsidises 3G data traffic with revenue from its core voice and SMS business. This means, says Song, that when it comes to communication, "the poor in South Africa are effectively subsidising the wealthy".

Song also invites us to consider "the microeconomics of the edge cases of mobile access" - the case of a remote village served by a single cell tower. He contends that in this scenario, the majority of calls made would be to other users in the same area, i.e. local calls. Song also asserts that people in Africa "are spending substantial amounts of their disposable income on access." So, he argues, if, say 50% of the phone calls made in a remote village are local and if people are spending 50% of their disposable income on mobile access, "that means that 25% of their disposable income is being siphoned out of that village."

Perhaps with my own mobile bill in mind, I initially wondered whether it could really be true that even very poor people could possibly be spending as much as 50% of their disposable income on voice and SMS. Apparently so, according to a 2008 report from Research ICT Africa, a twenty-country network hosted by the EDGE Institute in Johannesburg and funded by Steve Song's former employers, the IDRC.

We can see from the table below that the report has indeed identifed African countries where consumers spend more than 50% of their disposable income on mobile services. These include Kenya (52.5%), Nigeria (52.4%) and Zambia (60.3%). According to this study, for the same three countries, the percentage of disposable cash spent on cellular services for the bottom 75% of the population by disposable income rises to 63.6%, 60.9% and 73.9% respectively.
Is this phenomenon - people spending such a major chunk of their incomes on mobile phone charges - purely an unavoidable consequence of how poor these people are? Or might more competitive mobile markets deliver considerably lower prices, thereby freeing up African consumers' cash to be spent on other items?

Several times, a DevelopingTelecomsWatch piece has focused on a particular country and voiced the idea that perhaps that state's mobile market is currently contested by too many cellcos - too many in the sense of not all of them being able to turn a profit and justify further investment. In the few months since this blog's inception, that question has been raised about Cambodia and Sri Lanka and about Tanzania, Burundi and Gabon.

Along the way, I've sometimes been quite critical of operators with aggressively low pricing. Metfone (the Cambodian subsidiary of Vietnamese MNO Viettel) is one example. I have expressed the view that Metfone's distribution of free SIMs and airtime is a "disruptive" market entry strategy which is "very nice for quickly building a subscriber base, but taken to its logical conclusion this can seriously erode overall market value for all players."

What I've had in mind is an idea I've heard articulated countless times at many, many telecoms industry conferences - that telecoms groups will only invest in and improve the communications infrastructure of those countries where good profits can be earned; that most operators naturally settle around a band of prices which enable profitable operation and happy shareholders for all competitors; that operators which sell their services below the lowest end of that band of prices can be accused of destroying martket value and threatening the ability of others to keep investing; that regulators/governments which allow any market actors to do this are not acting responsibly.

Steve Song would presumably not sympathise with these sentiments because he rails against the failure of telecoms regulators in Africa either to license enough new market entrants or to curb the excesses of incumbent players with significant market power. He feels that this has led to a situation where existing operators "collude to maintain high profits", citing the global price of SMS per byte vs. the true cost of delivering text messages.

The ODI's Rohit Singh also deals with the role of telecoms sector regulatory agencies in developing countries. He writes about how governments should oversee such issues as interconnection between the operators, spectrum allocation, and access to the international gateway. He argues that the importance of this role is shown when, in the absence of regulated interconnection tariffs, dominant firms charge high prices for connecting calls from other networks. Singh asserts that this limits effective competition, with dominant firms earning monopoly profits, keeping their prices high, and having little incentive to expand or innovate.

Without effective regulation, Singh continues, ownership of bottleneck infrastructure by dominant firms can diminish the developmental impact of the mobile sector by pushing up prices and restricting coverage.

When Singh reaches for an example of this kind of failure of regulation, he thinks of Zambia, where he says international calls are very expensive because the state-owned fixed-line operator charges high tariffs to private operators to access the international gateway. This distortion, he argues, then affects the domestic calls market, because private operators have to subsidise their international calls to compete with the public sector firm. In this characterisation, private sector mobile operators are the good guys of the piece, forced rather than inclined to charge high prices for their services. My feeling, then, is that Rohit Singh and Steve Song have quite different views of the optimally desirable interplay between telecoms operators and regulators.

Going beyond the issue of pricing, in an earlier blog post, Song expresses concern about how mobile operators in developing countries might conceivably take advantage of the ways in which cellphones have become indispensable in people's lives. Drawing on a March 2009 presentation by Nathan Eagle, the developer of crowdsourcing application txteagle, Song observes that no one in Kenya can afford not to have a mobile phone because "even if you are digging a ditch by the side of the road, day labour is now organised via SMS." Song feels that this means that mobile operators have Kenyans by the throat. To support this argument, he discusses another anecdote from Nathan Eagle's talk, which concerns a water pump manufacturer in Kenya that, by combining an M-Pesa-enabled, solar-powered metering system with their water pumps, has completely changed its business model. This company is apparently now giving water pumps away for free and then making a profit by selling access to water through the M-Pesa service. In his presentation, Eagle observes that Michael Joseph, the CEO of Safaricom, "loves this because you have to have a Safaricom account to get water."

Steve Song ask whether he is alone in finding this a little disturbing and feels that there is something wrong about a single mobile operator acting as the gatekeeper to water supply. Song argues that "for any village in this situation, Safaricom can charge whatever they like".

When I stumbled upon Steve Song's blog, I felt it would be interesting to draw attention to the uncomfortable questions which he raises. After all, DevelopingTelecomsWatch was never intended as a cheerleader for a particular view of the role of the communications sector in developing countries and emerging markets. So, for anyone else who has so far been unaware of Song's writing, I hope it has been refreshing to consider the ideas of someone who observes the actions of mobile operators with a critical eye. What I like about Song's writing is that his arguments are not weakened by an unattractively shrill tone. However, if you're curious to hear from someone who really doesn't mince his words about cellcos, I'd suggest you read a recent article by Llewellyn Kriel about South African operators and the country's telecoms regulator.
Share/Save/Bookmark

Thursday, 20 August 2009

Cellco-branded mobile banking to thrive without challenge?

If you were asked to reach for an example of mobile financial services gaining traction really impressively, perhaps you would think immediately of the M-Pesa service offered by the Kenyan cellco Safaricom, in which Vodafone owns a minority stake.

I daresay most readers are somewhat familiar with the service. For those who are not, Safaricom's TV advertisement provides a concise demonstration of the simplicity and utility of M-Pesa:


Since its launch in 2007, M-Pesa has attracted widespread praise. In February 2008, the 'send money home'-themed marketing campaign, of which this ad was a component, scooped the 'Best Broadcast Commercial' gong at the annual Global Mobile Awards ceremony hosted by the GSM Association. This year, 'Best Mobile Money Service' was introduced as a new award category at the same ceremony - Safaricom and Vodafone were joint winners. More recently, M-Pesa has been feted by UN-HABITAT, the United Nations agency for human settlements whose mission is to promote socially and environmentally sustainable towns and cities with the goal of providing adequate shelter for all. In June, the agency announced the first Habitat Business Awards for best practice in categories including affordable housing, clean urban energy solutions and innovative ITC solutions. In the latter category, Safaricom made the winning submission for M-Pesa, which the jury felt boosts urban entrepreneurship and clearly demonstrates the impact of innovative IT solutions for sustainable urbanisation.

In its submission to the judges, Safaricom mentions Kenya's large 'unbanked' population - people, largely from the urban poor, to whom opening a bank accounts is off limits. The submission document explains that such people face challenges around the safety of carrying cash (mugging and carjacking are cited as dangers they face) and the high cost of transferring monies to relatives in rural areas via existing channels.

The benefits for the consumer, then, are quite clear - but what does a mobile operator such as Safaricom gain from entering the mobile money space? Dawn Marshallsay of mobileSQUARED, writing in January, emphasised how mobile financial services drive up cellphone usage. She also quotes Safaricom CEO Michael Joseph, who told delegates at a London conference that "banking is a value-added service for mobile, not a money-making product"

"The main purpose of mobile banking is getting the customer to have an emotional attachment with the operator as they entrust their monetary details with the operator. Customers then start using their phones more in general," Joseph continued.

Where one operator in a developing country achieves differentiation as the only provider of such services, benefits for that operator, then, would presumably include achieving a high degree of customer stickiness in a market where the vast majority of mobile users are highly price sensitive (due to their relative poverty vs. their counterparts in developed countries) and where prepaid plans are dominant.

This model, in which consumers are locked into a specific mobile operator's set of financial services, is open to challenge, however. Earlier this month, Richard Wray of the UK's Guardian newspaper wrote about a recently-announced deal between mobile banking firm Monitise and Paynet, a company which operates ATMs and electronic payment services across Kenya, Tanzania and Uganda in partnership with thirty-five banks. Wray writes that the deal "will bring financial services to millions of people in Africa for the first time". The suite of services will include checking balances, moving money between accounts, and enabling customers to fill a mobile-wallet with cash to pay bills or send money to relatives.

A pretty close resemblance to M-Pesa and other mobile operator-run services, then. The crucial difference emphasised by Wray, though, is that while operator-branded services demand that users are customers of a particular MNO or are connected with a specific bank, the Monitise system is open to any financial institution and any mobile phone network that wants to plug into it. If I have understood this correctly, it seems, then, that M-Pesa and rival services such as Zain Kenya's Zap are to be challenged by an operator-neutral alternative. Monitise CEO Andrew Lukies believes that "mobile money is most effective as an 'open ecosystem' where you can transact with anybody or any organisation, regardless of your bank or mobile operator. Another differentiator, according to the Monitise Group's press release on this deal, is that "uniquely among mobile banking services, [it] enables people without a bank account to use its services, as well as providing traditional mobile banking to those with accounts."

It remains to be seen how far operator-neutral services of this sort pose a competitive threat to cellco-branded solutions such as M-Pesa, Zap, Orange Money (launched by France Telecom's mobile operation in Côte d'Ivoire) and the service launched by MTN Uganda in March, which the South African group hopes to roll out across its African footprint.

Assuming any such threat can be withstood, services like M-Pesa - improving the lives of the unbanked while providing cellcos with a customer retention tool - seem to be good for consumers, good for society and good for the operator.

None of this is to suggest that M-Pesa and services like it are never subject to criticism or concerns around their reliability and security.

Earlier this month, writes Victor Juma of Kenya's Business Daily, a technical hitch in the M-Pesa service caused anxious customers to crowd at outlets to have their accounts updated. For several days, it seems, users were unsure of whether some transactions had been properly credited to their accounts.

The service also appears to have been targeted by organised criminals depositing counterfeit currency via M-Pesa agents. Kenya's Daily Nation newspaper reported on 4th August that staff in two bureaus in the towns of Kutus and Kianyaga had received fake money worth Sh29,000 (about USD 380). Accounts used by the fraudsters were topped up without agents spotting the counterfeit cash. I assume that fraudulent deposits of this kind can be stopped once noticed, but this incident demonstrates that no system is completely immune from human error. Having visited Kenya, but never having stepped inside a retail bank there, I have no idea whether counter staff in banks there are more highly trained than M-Pesa agents and therefore less prone to making mistakes of this kind. Whatever the case, my feeling is that if mobile operators in developing countries are to capitalise on consumers' lack of access to traditional financial services and institutions, the authorities in those countries would be justified in insisting that the cellcos' services are subject to many of the same regulations imposed on the banking sector. I daresay, however, that incidents like the two mentioned here are relatively rare, so none of these observations are meant as a very serious criticism of mobile financial services in developing countries.

Kenya - and more specifically Safaricom's M-Pesa - stands out as a mobile money success story. How far is it an exceptional story? Can we expect services of this type to face greater obstacles to consumer acceptance and commercial success in other developing countries?

Sarah Rotman of the Consultative Group to Assist the Poor (CGAP) could presumably take a view on this, having written in July about the question of whether the success of mobile banking in Kenya can be replicated in neighbouring Tanzania. Rotman notes that unlike the rapid service uptake and quick development of an agent network in Kenya, things have moved much slower for Vodacom’s M-Pesa product in Tanzania. Explanations offered are as follows:
  • Geography/demographics: Tanzania is a less densely populated country than Kenya, which is important in light of the idea that the density of an agent network is a key factor in the success of any mobile financial services suite.
  • Market and competition: Safaricom in Kenya dominates its market (77.59% market share as of June 2009, according to WCIS), holding its own very well against established competitors and new entrants. Vodacom in Tanzania has just a 35.28% market share (according to WCIS) and is losing ground to the local operation of the Zain group and Millicom International Cellular's Tigo-branded operator.
  • Control over agent networks: according to Rotman, it appears that Vodacom Tanzania has less direct control of and influence on its airtime distribution channel than Safaricom. Also, Vodacom works directly with just six airtime wholesalers, compared with 300 for Safaricom. Safaricom’s airtime distribution network was a key element in the rapid development of the M-Pesa agent network.
  • Marketing and strategy: Initial Vodacom M-Pesa marketing seems not to have communicated the easily understood 'send money home' message we say in the Safaricom advertisement. As a result, writes Rotman, customers were unsure of what the product offered them and if it was really geared at the average Tanzanian.
While there are plenty of reasons to be bullish about the success prospects of mobile money services offered by cellcos to unbanked people in developing countries, then, it seems this enthusiasm should perhaps be tempered by an awareness of possible competitive threats from operator-neutral solutions and an understanding that a one-size-fits-all approach might not work effectively across a multi-country footprint.
Share/Save/Bookmark

Wednesday, 24 June 2009

Zain Africa Speculation Watch: Episode 6

For an entity supposedly up for sale and coveted by a wide variety of interested parties, Zain's African unit has certainly been very busy creating new partnerships and gaining publicity for its various activities.

One example of this, brought to my attention by TelecomPaper this week, is the operator's cooperation with Western Union, whereby the two organisations will work together to deliver mobile money transfer services in countries in Africa and the Middle East through Zain's new Zap platform. The service enables Zain subscribers to manage their bank accounts, top up mobile airtime (and transfer airtime to other subscribers), pay utility bills, pay for goods in retail outlets, and transfer money to friends and family.

The opportunity around providing financial services to the unbanked in Africa and in developing countries worldwide is a certainly a rich one. At the Mobile World Congress in Barcelona earlier this year, GSM Association CEO Rob Conway observed that "there are over one billion people in emerging markets today who don’t have a bank account but do have a mobile phone." Conway feels that mobile operators "are perfectly placed to bring mobile financial services to this largely untapped consumer base" and that "mobile money for the unbanked has the potential to become a USD 5 billion market opportunity over the next three years."

Conway was speaking during an announcement made jointly with the Bill & Melinda Gates Foundation, which provided a USD 12.5 million grant to the Mobile Money for the Unbanked (MMU) programme, the aim of which is to "encourage the expansion of reliable, affordable mobile financial services to the unbanked."

With Rob Conway having set out the scale of the opportunity for MNOs, the Foundation's Bob Christen was keen to stress the humanitarian benefits, noting that "technology like mobile phones is making it possible to bring low-cost, high-quality financial services to millions of people in the developing world so they can manage life’s risks and build financial security."

Mobile financial services then, should surely be a vital component of the strategy of any telecoms group whose operations are, in large part, in developing countries - a nice revenue opportunity plus wonderful CSR benefits around poverty alleviation.

Setting up services of this kind, however, can be challenging. The last time I heard this discussed at a conference (East Africa Com in Kenya this April), delegates were asking questions about regulatory complexity and about to what degree securing the necessary participation of established financial institutions was going smoothly.

Bearing this in mind, it is perhaps worth noting that while Zain's announced partnership with Western Union sounds exciting, much of the text refers to this being a work in progress - not yet fully operational and subject to regulatory clearance in countries worldwide.

This leads me to wonder whether it would be sensible to dedicate considerable efforts to this venture if up to sixteen of the operations in which the service will work are really to be sold in the near future.

Another initiative possibly set to do wonders for Zain's image as an organisation committed to improving lives in Africa was announced only days ago. Dubbed "Weather Info for All", this involves Zain, Ericsson, the Global Humanitarian Forum and the World Meteorological Organization. The aim is to "radically improve Africa’s weather monitoring network in the face of the growing impact of climate change," which is said to be responsible for some 300,000 deaths worldwide each year and over USD 100 billion of economic losses, mainly because of shocks to health and agricultural productivity. As the Weather Info for All announcement indicates, "Sub-Saharan Africa accounts for close to a quarter of these losses, and is the region at the most immediate risk of droughts and floods."

Africa suffers not only from the effects of these adverse weather conditions, but also from a dearth of reliable information about when and where disaster is likely to strike. This is due to the continent having a weather monitoring network eight times below the WMO minimum recommended standard, and less than 200 weather stations that meet WMO observation requirements, compared to several thousand each in Europe, North America, and parts of Asia.
The Weather Info for All initiative is aimed at adding 5000 weather stations across Africa. Zain has got the ball rolling by providing access to tower sites in Kenya, Tanzania and Uganda.

Mobile network infrastructure provides an unrivaled wealth of support for weather stations - connectivity, power supply and security.

Ericsson, meanwhile, will develop mobile applications to help communicate weather information via mobile phones to the vulnerable communities whose lives can be wrecked by adverse conditions.

I know less about the levels of investment and commitment required of Zain with regard to the Weather for All Initiative than I do about the amount of hard work needed to roll out mobile financial services for the unbanked. Both initiatives, however, have in common a sense of being long term endeavours. Again, I ask whether all of this activity might suggest that the sale of Zain's African operations is rather unlikely.
Share/Save/Bookmark

Tuesday, 23 June 2009

South Africa, East Africa gear up for vastly improved capacity

Back in April, I wondered about the impact of the three undersea cables set to land in East Africa - SEACOM, EASSy and TEAMS. I explored the question of whether it really mattered which cable would land first. I also thought about whether the region's hitherto inadequate broadband supply means that there is room for all three. I was quite attracted to the line of argument that there is.

With a few related news items popping up this week, I thought it was high time I had another look at these questions.

SEACOM appears to be very close to completion, with the company's website currently indicating that the service will be fully operational in sixteen days' time. The company has also received warm words of support from a South African customer excited about a "shift towards a high speed, high capacity Internet connectivity environment".

Hillel Shrock, Business Solutions Director at ISP/telecoms service provider Internet Solutions, believes that "Seacom is an important milestone for the local telecommunications industry as it is the first time that South African service providers, other than Telkom, will be able to make a long term investment in the provisioning of high speed, high capacity international connectivity."

In Kenya, meanwhile, telecoms sector players are working out strategic partnerships designed to take full advantage of TEAMS becoming operational. Cedric Lumiti of East African Business Week, wrote this week about the deal struck between market-leading Kenya MNO Safaricom and Jamii Telecommunications, whereby the latter will become the cellco's preferred broadband infrastructure provider. Safaricom CEO Michael Joseph explains that his company has now formally migrated to the new technology-neutral unified licensing regime set out by the Communications Commission of Kenya and can therefore offer a broader spectrum of data services using any technology platform.

All very upbeat - in line with the positive noises I heard at April's East Africa Com conference in Nairobi. If my travels take my back to that part of the world once all the cables have landed and have brought vastly greater capacity online, I'll be interested to learn about how quickly this begins to stimulate economic activity. It will also be good to get a faster connection in my hotel. VPN access was just impossible last time - and there was a lamentable slowdown in Developing Telecoms Watch blogging activity.
Share/Save/Bookmark

Thursday, 18 June 2009

Zain Africa Speculation Watch: Episode 3

Zain-branded retail store in Uganda: needing a new paint job soon?
(image from Honeysun blog)

Telecoms media news sources, analysts and bloggers continue to be divided on the issue of whether there is much substance to the rumours about Zain looking to sell its African assets. Some commentary about this story, which, for me at least, popped up seemingly out of nowhere last week, continues to express a high degree of skepticism. The tone of some writing, meanwhile, seems to present Zain's desire to offload the former Celtel International operations pretty much as a given, focusing on quite detailed analysis of particular challenges that will have to be faced during the process.

Zambian journalist Michael Malakata, for example, writes in terms of how "Zain's efforts to sell its African operations" are likely to be hampered by problems such as a move by Econet Wireless Group to block the Nigerian element of the deal. Just as Malakata's article seems built on the assumption that Zain's exit from the African scene is actually going to happen, he also seems very sure that Orange/France Telecom is set to acquire the sixteen mobile operators supposedly up for sale - rather than Vivendi, whose name has been bandied about very freely these last few days.

Adam Durchslag of Reuters, conversely, seems more interested in examining the case for Vivendi being involved and gets a big thumbs up from me for making a pun of the word za(i)ny in the title of the blog post he wrote yesterday. I avoided the temptation to do so myself, but only just.

In his article, Durchslag picks up on widespread bemusement about how getting out of Africa would make sense in the context of Zain CEO Saad al-Barrak's recently stated ambition for the business to a top-ten global mobile operators by 2011.

With this in mind, Lesley Stones of South Africa's Business Day offers some useful thoughts on what could drive any sale, asserting that while Zain’s African operations accounted for 65% of its subscribers and 56% of revenue in 2008, "they absorb more than 75% of its capital expenditure, yet only account for 15% of net income." Stones states that "while Zain’s net income rose just 6% last year, if Africa had been excluded it would have been up 34%."

Adam Durchslag, meanwhile, considers the idea of a rather different kind of Zain-Vivendi tie-up potentially being on the cards, such as Zain taking a minority stake in the larger French group. If there is any substance to rumours of these two companies being in talks, perhaps that scenario is more likely than Vivendi simply buying operations from Zain. As Durchslag notes, it is worth considering Vivendi's ability to afford a USD 12 billion transaction. He points out that the French group has about EUR 8.3 billion of net debt and, "according to some analysts, has only EUR 1 billion for manoeuvre without jeopardising its investment grade BBB credit rating."

Durchslag then considers another possibility - that of Vivendi, through its Maroc Telecom subsidiary (which owns telcos in Mauritania, Burkina Faso and Gabon) buying only some of Zain’s African operations.

This raises of the question of whether Zain could conceivably be open to the possibility of breaking up its African operation and selling assets piecemeal to groups looking to fill gaps in their pan-African footprints - rather than a single transaction in which the whole lot are sold to a single buyer. Kenyan newspaper the Daily Nation carried rumours on Tuesday that Zain's Kenyan outfit "could end up in the hands of MTN Group, the powerful South African transnational." The article asserts that "MTN has for years been known to covet the Kenyan market", having previously tried and failed to buy the operation now known as Zain Kenya.

Writing for another Kenyan newspaper, Macharia Kamau considers MTN as a possible suitor, but spends more time considering the Vivendi option. In the spirit of Alanis Morisette, Kamau feels that if Vivendi succeeds, this would mark an "ironical" return of the company to the Kenyan market. Kamau reminds us that Vivendi sold a 60% stake in KenCell (the predecessor of today's Zain Kenya) in 2005. Any loyal Kenyan subscribers of this operator's services, therefore, are already on third brand name in a four year period. A further transaction could mean four brands in four years - that's almost as confusing as the regularity with which my favourite football club hires and fires managers.

Even this high degree of brand name turnover, however, would be trumped in Nigeria. Writing for that country's Vanguard newspaper, Prince Osuagwu, notes that if "Zain Group finally agrees to sell its Celtel Africa unit to a bidding French media conglomerate, Vivendi SA this week, the Nigerian operation of the company may be heading for the 6th... name change."

Osuagwu spoke with Zain Nigeria subscribers and reports some discontent at the prospect of yet another rebranding, feeling that some might switch to rival service providers because of "fears that the network might not catch up with competition after going through [the] image crisis that may possibly follow."

Thanks for bearing with me on another long-ish ramble through the Zain empire as I try to figure out whether this is a hot story, a non-story or something in between. There's bound to be a least one more episode in this mini-series. Don't touch that dial. No flipping.
Share/Save/Bookmark

Friday, 29 May 2009

Where will MNP go live in 2009? How should MNOs respond?

With Mobile Number Portability now about to hit the Indian market, the country's technology media are following the debate about how much impact this is likely to have.

Jatinder Singh, writing for Voice & Data magazine, notes that MNP has been a long time coming:

"After years of discussions and apprehensions by major telecom operators, MNP or mobile number portability, is finally going to make inroads into the Indian telecom market. [The] TRAI has approved the pan-India implementation of MNP, and [the] DoT has framed the timeline of its implementation; it is expected to hit the market by year-end."

Singh notes that MNP will be phased in piecemeal, region by region, starting with Delhi, Mumbai, Kolkatta and Chennai, with nearly 18% of the total cellular subscriber base given the option to change service providers while retaining their current mobile numbers. Singh also expresses the opinion that MNP may force operators to improve quality of service in order to avoid losing customers to rival MNOs.

So, how seriously are India's operators taking MNP in terms of threats and opportunities it might create? A range of views are reported in Jatinder Singh's article:

Kuldeep Goyal, Chairman and MD of BSNL, which currently occupies 4th place in terms of mobile market share with 11.95% of subs according to WCIS, seems upbeat about MNP, saying "It would certainly offer opportunities in the Indian telecom market. We are positive with our market share and would be eyeing more customers once things are in place."

From market-leading Bharti Airtel, Dr Jai Menon (Director, Customer Service and IT) notes that MNP has had varying levels of impact in markets worldwide.
"We are ready and believe that it allows more and more customers to come to our network and enjoy the services," says Dr Menon. Also speaking for Bharti Airtel, Deputy CEO Sanjay Kapoor told the Business Standard earlier this month, that MNP "is more relevant in countries where you have long-term contracts", going on to explain that because "India is a prepaid market... number portability won’t be a game-changing opportunity for anybody." For Kapoor, the vast, price-sensitive prepaid segment is already so inclined to regular churn with "the exit and entry cost on prepaid connections... so low", that he does not believe MNP "really adds to value."

It is, perhaps, tempting to assume that a newer market entrant would be welcoming MNP much more enthusiastically, mindful of an improved opportunity to grab customers from established rivals.

Raymond Yu of telecoms think tank Ovum, writing earlier this month, however, contends that all MNOs are vulnerable to MNP-driven churn. He cites the cases of Greece and
Lithuania, where the largest operators actually managed to increase their market shares immediately following the introduction of MNP. Yu also recalls the case of Hong Kong, where although all MNOs experience a large number of ports, "this is not unique to the customers of the market leaders."

In India, considerations of this kind may account for the apparently quite muted repsonse of new kid on the block Sistema Shyam Teleservices. The Voice & Data article quotes Vseovolod Rozanov, the company's CEO, as saying "it is more of an opportunity than a threat. However, looking at the experiences of global markets, the influence on change in the market share is not very dramatic." This is not to suggest, however, that Rozanov is completely disinterested in MNP. In a recent Economic Times article he is quoted as saying "
number portability will... drive growth for us." The Sistema-backed operation, which has now harmonised its brand with that of the giant Russian cellco which is part of the same group, has, according to WCIS, yet to break the 1% mark in terms of market share.

The Bharti Airtel CEO's comments about market conditions in India somewhat diminishing the relevance of MNP are echoed, to a degree, by remarks made by the head of the telecoms regulatory agency in Uganda. In this case, however, market size rather than the behaviour of prepaid users is being put forward as the argument against imminent deployment of MNP.

A recent Cellular News story quotes
Patrick Masambu, Executive Director of the Uganda Communications Commission, as saying that "at this stage, number portability is not something we see as a remedy in this market." Mr Masambu feels that the Ugandan market needs to grow further before the costs could be justified. He added, however though that once the country has passed the 10 million subscriber mark, then MNP could be viable. I find it a little curious that Mr Masambu chooses 10 million subs as the trigger for more actively considering MNP. If you read his comments without knowing the size of the Ugandan mobile market, you might imagine that the country has rather fewer than the 10 million subscriptions. According to WCIS, however, the country had 9.95 subs as of March this year. Hmmm...

In neighbouring Kenya, the deployment of MNP may also be some way off, if a recent article from the country's Standard newspaper is to be believed. The Standard's Robert Ndingwa notes that the Communications Commission of Kenya (CCK) has just three months to go before its September 2009 deadline to implement its version of number portability but states that the regulator is yet make a decision on whether to licence local number portability operators, "leaving consumers at the mercy of dominant mobile service providers." Ndingwa alleges that the CCK "prefers, instead, to hide behind its so-called principle of technology neutrality in the new market structure it introduced."

With some operators and regulators apparently lukewarm about the need for and effects of MNP, it might be worth asking whether views of this kind might mask a degree of fear about number portability. If so, Ovum's Raymond Yu dvises operators in particular not to be too worried, suggesting that each MNO must decide whether to view MNP as a threat or an opportunity and then devise an effective strategy in response.

Yu argues that "essentially, there are two ways to react to the introduction of MNP: either promote it or keep it under covers." In most cases, challenging operators would take the aggressive stance, says Yu, "whereas dominant operators are initially more reluctant to push MNP."

Yu notes that popular strategies for promoting MNP include making it a normal part of the sales process and using marketing to increase consumer awareness and perception of the facility to retain their numbers when switching providers. Strategies to defend against MNP include, according to Yu, simply not advertising it, implementing strong win-back strategies in line with porting requests and employing stronger loyalty and retention initiatives.

Let's see which of these options are chosen by MNOs in India - and in Uganda and Kenya, should MNP become a reality any time soon. According to Raymond Yu, other markets to watch for MNP deployments this year include Ecudaor, the Dominican Republic, Peru and Thailand.

Share/Save/Bookmark

Tuesday, 12 May 2009

CDMA to GSM migration: another one jumps ship in Africa

Reports of the death of CDMA have been greatly exaggerated. That has been the theme of of few articles I've posted here. In March I blogged on claims made about the standard being in rude health in Nigeria. A month earlier, I was writing about operators betting on CDMA in India. That article, however, did report on the seemingly unstoppable rise of the GSM family and the constantly eroded global market share of CDMA. Contributing to this trend is the phenomenon of former CDMA operators migrating to the more successful technology. An example of this is currently underway in Africa.

I learned via Telegeography yesterday that Rwandan mobile operator Rwandatel is continuing to switch users from CDMA mobile phones to 3G-enabled GSM handsets.

According to the article, which quotes RwandaTel CEO Patrick Kariningufu, the MNO is handing out new GSM handsets to an estimated 20,000 subscribers mainly located in rural areas. The move is said to be part of the company's response to increased competition.

The country's mobile market is currently split two ways - but the slices are very differently sized. MTN's Rwanda outpost has 82.61% of the country's subscriptions according to WCIS. Until late last year, Rwandatel, as a purely CDMA operator, was doing OK in terms of slowly chipping away at MTN's dominant position. The decision to migrate to GSM/W-CDMA was made some time ago, however. A Global Mobile Daily note of December 5th indicates that while the new network was launched around that time, the operator, a unit of Libya's Lap Green, had hoped to make the move to GSM earlier last year but was prevented from doing so by equipment shipping delays caused by the post-election violence in Kenya.

Both cellcos will be preparing for the impact of a new challenge to the status quo. This comes in the form of a soon-to-be-launched Tigo-branded MNO, the newest part of the Millicom International Cellular empire.

In November, GMD reported that Millicom had been awarded Rwanda's third mobile operating license by the Rwanda Utilities Regulatory Agency, which reportedly rejected competing bids from Zain and Telecel Globe, a company owned by Orascom Telecom. Millcom's new operation will offer mobile and fixed-line services.

Market-watchers will be interested to see if Rwandatel's migration to GSM will be enough for the operator to compete effectively vs. this new entrant and the well-established MTN operation.
Share/Save/Bookmark

Monday, 11 May 2009

Advice for emerging markets cellcos looking to replicate the success of M-Pesa

I am fortunate to be receive, on a regular basis, very insightful reports from the TIME practice of management consultants Arthur D. Little. The most recent of these is upbeat about m-payment services. Some advice is offered to the various value chain players in emerging and developed markets. For the former, the advice seems to be directed largely at mobile opertators, from which we might infer that MNOs have the opportunity to establish themselves as the key players in developing countries.

Mobile operators, attracted into the m-payment space by minimal competition from conventional payment-channels in emerging markets, are advised to take "an active role in shaping the regulatory environment" because the competing financial industry may lobby for policies and regulatory mechanisms designed to keep MNOs at bay. Mobile operators are also urged to "focus on low value/high frequency transactions and have a special focus on remittances". Finally, Arthur D. Little advise operators to continue to build up cross-border partnerships to ensure cross-border interoperability of remittance services across emerging markets.

In March telecoms.com ran a feature which noted that mobile financial services have continued to gain traction, particularly in developing countries.

"Mobile financial services fall into two distinct camps; additive and transformational banking", states that article. Additive banking is defined as "services targeted at markets that already have traditional financial services at their disposal." Transformational banking is defined as "the practice of extending banking and payment services to those people who do not have ready access to banking facilities" - i.e. largely people in developing countries or migrant workforces in more developed countries.

The article notes that transformational banking is currently grabbing a good deal more column inches than additive banking and cites the well-known example of M-Pesa, initially launched by Kenyan cellco Safaricom and later launched in Afghanistan and Tanzania by MNOs Roshan and Vodacom Tanzania respectively.
Share/Save/Bookmark

Sunday, 12 April 2009

Kenya: Zain and Yu cut costs through infrastructure sharing

Having very recently been to Kenya for the first time, I now find stories from that country catching my eye.

One which has broken since my trip, reported by Telegeography among others, concerns a network infrastructure sharing deal struck by Zain Kenya and Essar Telecom Kenya (until recently known as Econet Wireless Kenya).

In February, I asked here
whether 2009 will see arrangements of this type having a major impact in emerging markets worldwide. I cited recent examples from India, Bangladesh and Panama, but noted that in Zambia, Zain had declined to become involved in a network sharing project recommended by that country's telecoms regulator in order to boost rural coverage. Zain Zambia and prospective network sharing partner MTN Zambia preferred to spurn the approach from the regulatory agency on the grounds of guaranteed quality of service being a difficult issue.

Zain's Kenyan operation appears to have no such qualms, with reduced base station operating costs being cited in local reports as the principal driver for the cellco entering the infrastructure sharing deal with the Yu-branded recent entrant.

This presumably meets with the approval of the Communications Commission of Kenya, whose Assistant Director Susan Mochache spoke at the East Africa Com conference I recently attended. Ms. Mochache's presentation made mention of infrastructure sharing as a plank of the Commission's wider strategy of promoting competition. Ms. Mochache was asked during the conference about whether network sharing was something the Commission would be merely recommending or whether it might do some degree become mandatory. The answer, however, was not immediately clear to me. I think I understood that this is an issue which is still under discussion.
Share/Save/Bookmark