News, views and commentary from the telecoms sector across emerging markets and developing countries worldwide
Showing posts with label Starcomms. Show all posts

Friday, 19 March 2010

East African opportunities unclear as cellcos remain coy about data ARPU

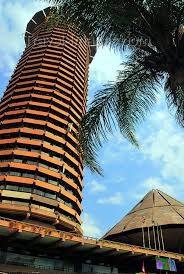
Kenyatta Int'l Conference Centre, Nairobi: venue for this year's East Africa Com

Last year I had the pleasure of visiting Nairobi, Kenya for the first time, building meetings around the excellent East Africa Com conference and exhibition.

This year, given that my day-to-day commercial activity now does not give me much exposure to Africa, I will not attending. Were I still more active in Africa, however, I would certainly want to be there - and I would encourage anyone who does business with the telecoms operators of the East Africa region to head for the Kenyatta International Conference Centre on 27th-28th April.

This year's event will be graced by the presence of the Hon. Samuel Poghisio, the host country's Minister for Information & Communications and by Charles J.K Njoroge, Director General of telecoms regulatory agency the CCK (Communications Commission of Kenya). I don't recall the Kenyan Government and authorities being represented at such a high level at the 2009 event, so the organisers are to be congratulated for the upgrade.

Sponsors and exhibitors will doubtless also be impressed by the number of operator CEOs to whom they will have access during the two days of discussions. Of these, two of the biggest hitters are Michael Ghossein, CEO of France Telecom-controlled Telkom Kenya, the country's incumbent fixed-line operator and Michael Joseph, the long-standing CEO of Kenya's dominant (78.8% market share, according to WCIS) mobile operator Safaricom.

This may be one of the final conferences appearances for the latter, Joseph having announced his impending retirement. He joined the Kenyan operator in mid-2000, when Vodafone first invested in the company. Since then, he has guided the company from a subscriber base of fewer than 20,000 to over 15 million today. Along the way, Safaricom has become renowned for its M-Pesa mobile money transfer service, which has brought the advantages of financial services to very large numbers of Kenya's largely 'unbanked' population. Safaricom also attracted praise this week from Alexander Grouet of Mira Networks, a leading provider of connectivity and billing tools between business and mobile networks in Africa.

Grouet asks: "Would you plan a trip to a foreign destination if you didn't know what the place looked like, what there was to see, how much a hotel room cost and what local transportation was available?" Having concluded that most readers would not, Grouet then invites us to imagine that what we’re talking about is not your vacation, but your business. "Well that’s pretty much what it’s like for most content providers wanting to penetrate the SSA [sub-Saharan Africa] market", he continues. "Despite the hype, the market metrics WASPs crucially need in order to make the next step, such as data ARPU or WAP traffic, are virtually inaccessible. Even traditional market data resellers don't offer it, as optimistically named Africa VAS reports almost exclusively include blended indicators rather than content-specific ones." I don't recall if this is a fair accusation to direct towards the good folks at the reports business of Informa Telecoms & Media, the organisers of East Africa Com.

Even if it is, Grouet suggests that the fault for the scarcity of these vital data lies with operators. "Out of the 26 operators in the 5 countries I worked on last year (Nigeria, Kenya, Ghana, Senegal and Cote d'Ivoire) only 2 to my knowledge," he writes, "publicly released their data ARPU." The two cellcos in Mr. Grouet's good books are Safaricom and Starcomms, a Nigerian CDMA carrier.

"The most likely explanation for this", ventures Grouet, "is that the data figures are still so low on most networks that operators simply don’t want to release them at this stage." According to Grouet, even Safaricom's data ARPU, including M-Pesa, stands at just USD 1 monthly, while the figure for Starcomms, including EV-DO dongles, is just under USD 2 per month. "But at least, we know where they stand, and we will be able to measure their progress when they next update those figures," Grouet continues.

Grouet hopes that other African operators will break their silence on the topic of data revenues, not least because that unwillingness to share data "only has the counter-productive effect of making it harder for international content companies, who precisely could help operators boost their data traffic, penetrate their markets."

Let's see how many cellco attending East Africa Com agree with these sentiments. Were I to attend this year, I would probably like to pursue that line of questioning, not least because I have received marketing emails from Informa which suggests that the region's operators are somewhat focused on data services.

A speaker likely to turn in an entertaining presentation is Noel Herrity, CEO of Tanzania's Zantel, an operator in which the UAE's Etisalat owns a 51% stake. Mr. Herrity delivered a compelling, nicely paced talk at the 2009 iteration of the conference and delegates will be hoping for more of the same. Perhaps we can be optimistic about that - Herrity may be in buoyant mood in light of recent reports indicating that the operator has begun recording net customer additions again, following two quarters of net loss.

One speaker for whom it could be challenging to stay 'on message'? Bashar Arafeh, the COO of the East Africa Region for MEA mobile group Zain.

This might arise as a result of delegates' curiosity about the future of Zain's African operations. Subject to takeover speculation for many months now (see DTW articles passim.), these assets could well be the property of giant Indian cellco Bharti Airtel before too long. The most recent developments in this long-running saga may soon prompt a revival of the popular mini-series (well, it generated more hits than usual) which appeared here on-and-off for much of 2009, rejoicing in the clunky title 'Zain Africa Speculation Watch' (and variations thereon).

Other CxOs appearing on stage at next months event include:
I'm sure this year's event will once again be a useful place to do business, gain market intelligence and enjoy the company of a crowd who always seem very open to networking and making new contacts.
Share/Save/Bookmark

Sunday, 1 March 2009

CDMA alive and well in Nigeria?

ZTE last week announced that its CDMA EV-DO Rev. B solution will be available for commercial deployment in Q3 this year. Kevin Fitchard of Telephony magazine reports that the Chinese vendor claims to have demonstrated the viability of dedicating an entire CDMA network to 3G while still supporting both voice and data. ZTE talks up the advantages of having circuit-switched voice capacity replaced with VoIP, claiming that Rev. B will have both the capacity and low latency to support high volumes of VoIP traffic.

However, as Fitchard notes, CDMA operators are not rushing forward in great numbers to deploy Rev. B, with many of the major players having already committed to deploying LTE networks. Notable, of course, is US giant Verizon Wireless, whose LTE plans are at an advanced stage. Fitchard argues that LTE will not only give CDMA operators the same wide channels as Rev. B, but it is also a more spectrum efficient technology, going on to predict that CDMA operators are likely to bypass Rev. B entirely and focus their broadband strategies on LTE.

None of this is to suggest that the CDMA networks themselves are set to become a thing of the past any time soon. OK, in a recent post here I noted that India's Tata Teleservices (as has been the case with its rival Reliance Communications) is looking to migrate customers from a legacy CDMA to a newer GSM network. I also mentioned the case of major Brazilian cellco Vivo being further down that same migration path. However, I have also written here about new entrant Sistema Shyam Teleservices wanting to acquire other CDMA operators in order to gain better access to the Indian market. In the same article, I noted that the COAI, the Indian GSM operators' trade association, has been protesting about the possibility of being outpaced by CDMA operators in the race to deploy 3G services.

In India at least, there appears to be life in the CDMA camp. Another market where the same can be said would appear to be Nigeria. Some CDMA operators there certainly claim to be in rude health, not least Visafone, a unified service licence holder which had launched commercial services in over forty cities across twelve states, including in the capital Abuja, by early 2008. According to a year-old Global Mobile Daily report, the operator gained its license following its acquisition of CDMA operator Cellcom in June 2007, going on to grow by purchasing further CDMA players Independent Telephone Network and Bourdex Communications in November 2007 and January 2008 respectively. These acquisitions gave Visafone a subscription base of around 100,000. According to an article that I stumbled upon today, the unified service licence held by the company, which was founded by Zenith Bank International CEO Jim Ovia, allows the provision of both mobile fixed telecoms services. This followed the 2006 expiry of a five-year mobile market exlusivity arrangement enjoyed collectively by the country's GSM MNOs.

By July 2008, my former Informa Telecoms & Media colleague Matthew Reed, editor of Middle East and Africa Wireless Analyst, was writing about Nigeria's CDMA operators experiencing "strong growth". Matt noted that the unified licensing system had liberated the CDMA players by enabling them to offer nationwide services, and pointed out that Starcomms, then (and still) the country's biggest CDMA, operator had seen its subscription count grow 125.5% in the twelve month period up to March 2008. Matt also observed that Multilinks, which is controlled by Telkom, South Africa's incumbent wireline operator, had, over the same period, enjoyed at 49.2% rise in its subscription count. Other numbers reported by Matt last summer: Reliance Telecom had recorded growth of 54.84% in the 12 months to end-March, to 430,000 subscriptions, and Intercellular and Visafone had both seen their subs counts more than double over the same period.

Despite these strong growth rates then, as now, the big three GSM MNOs remained much larger players. That notwithstanding, Visafone CEO Thomas Ninan was keen to direct some highly critical comments towards his GSM rivals when profiled by Nigeria's Technology Times in November. Ninan alleged that Nigerian GSM subscribers suffer QoS issues because the operators "commit an inadequate portion of the revenue they yield from the nation’s mobile telephony market on network expansion." According to Ninan, states the article, "in a bid to gain maximum return on their investments, GSM operators only spend a relatively marginal part of their revenue to network expansion, a development that has seen subscribers... suffer... network congestion."

Ninan was quoted as saying that Visafone was "exploiting opportunities created by GSM operators that are short-changing their customers". This particular comment was made in Mauritius, where Ninan was attending the 3rd Global CDMA Operation and Development Forum, hosted by Huawei, Qualcomm and the CDMA Development Group. In that setting, I imagine that Ninan may well have got a fairly sympathetic reception for his strong words.

Ninan feels that the leading GSM players, MTN Nigeria, Zain Nigeria and Globacom have set their tariffs "very high", which opens "more space for price competition."

To some degree, it now seems that the Nigerian Communications Commission concurs with Mr Ninan's view that mobile subscribers in the country could be served better. Last month, Technology Times reported that the NCC has found it necessary to inaugurate a 12-man Industry Consumer Advisory Forum to protect the rights of consumers of telecoms services. Organisations represented on this advisory boady include the Nigerian Society of Engineers, the National Disabled Empowerment Forum, and the Consumer Awareness Organzation. The Association of Telecommunications Companies of Nigeria (ATCON) is also represented, presumably in the interests of balance.

In terms of securing better deals for customers, one area of concern, according to Muhammed Rudman, Managing Director of Nigerian Internet Exchange Point (NIXP), is the high price paid by end users of Internet services. NIXP is a neutral, not-for-profit Internet exchange committed to enhancing the exchange of traffic between networks through co-operative peering agreements. According to another Technology Times report last month, Rudman has urged the Government to mandate all service providers to connect to the nation’s exchange points, adding that a Government-mandated connection rule "is a last-ditch recommendation following the apathy shown by service providers". Rudman feels that all service providers connecting to the nation’s exchange points is a vital component of achieving "technical and economic gains for the Internet community in Nigeria."

In the mobile space, Visafone's Ninan has not been the only highly vocal booster for CDMA technology. Ninan's counterpart at Starcomms is the Lebanese-American Maher Quabain, who, in a March 2008 interview with ITNewsAfrica.com, insisted that CDMA "consistently provides better capacity for voice and data communications than other commercial mobile technologies, allowing more subscribers to connect at any given time."

Perhaps the most bullish words on the subject of the Nigerian CDMA operators' prospects come from Reliance Telecom, whose Executive Vice Chairman Ken Aigbinode, speaking last summer, set his company the target of having acquired 10 million subscribers by 2011. This does, perhaps, look ambitious. The company's subscription numbers surged from 415,000 to 752,000 in the period Dec 2007-Dec 2008, according to Informa's World Cellular Information Service. For me, 10 million still looks like a quite distant milestone. That said, there is room for growth in the Nigerian market. Mobile penetration stands around 40%, and the country currently has a population of around 148 million. However, with no fewer than eleven mobile operators currently competing, and with the GSM players still a long way ahead, I do wonder how far the CDMA MNOs can grow. Of the GSM group, the newest, Etisalat Nigeria, is presumably well-funded, given the deep pockets of its majority shareholder from the UAE.

There are not many markets worldwide still hosting a GSM-CDMA struggle. Nigeria's looks by some measure the most interesting.


Share/Save/Bookmark